 11
Best Mutual Fund Investing Strategies for Long-Term Wealth | Complete 2025 Guide
Complete 2025 Guide ·
Why 9.2 crore Indian investors are betting on mutual funds and the specific strategies that separate the wealth builders from the crowd.
📅 Updated April 2025⏱ 18-min read👤 Certified Financial Planner
Here’s a number that stopped me mid-conversation at a client meeting last year: ₹54.54 lakh crore. That’s the total AUM under Indian mutual funds as of March 2025, according to data from AMFI (Association of Mutual Funds in India). In 2015, it was ₹10 lakh crore. That’s a 5x jump in a decade.
And yet, most people I talk to still aren’t sure whether they’re investing right. They’re putting money into funds, sure. But investing blindly and investing strategically for long-term wealth? Those are two wildly different games.
I’ve spent 14 years as a certified financial planner working with everyone from first-generation investors in smaller cities to high-net-worth families doing serious portfolio construction. I’ve watched people build crores through disciplined mutual fund strategies, and I’ve watched others panic-sell at exactly the wrong moment and lose years of compounding gains in a single bad week.
This guide is the comprehensive map I wish everyone had before they started. We’ll cover the core frameworks, the underrated strategies most articles skip, the comparison between approaches, and the specific tax-optimisation moves that can quietly add lakhs to your long-term returns.
Hang tight, the section on asset allocation frameworks alone might change how you think about your entire portfolio.
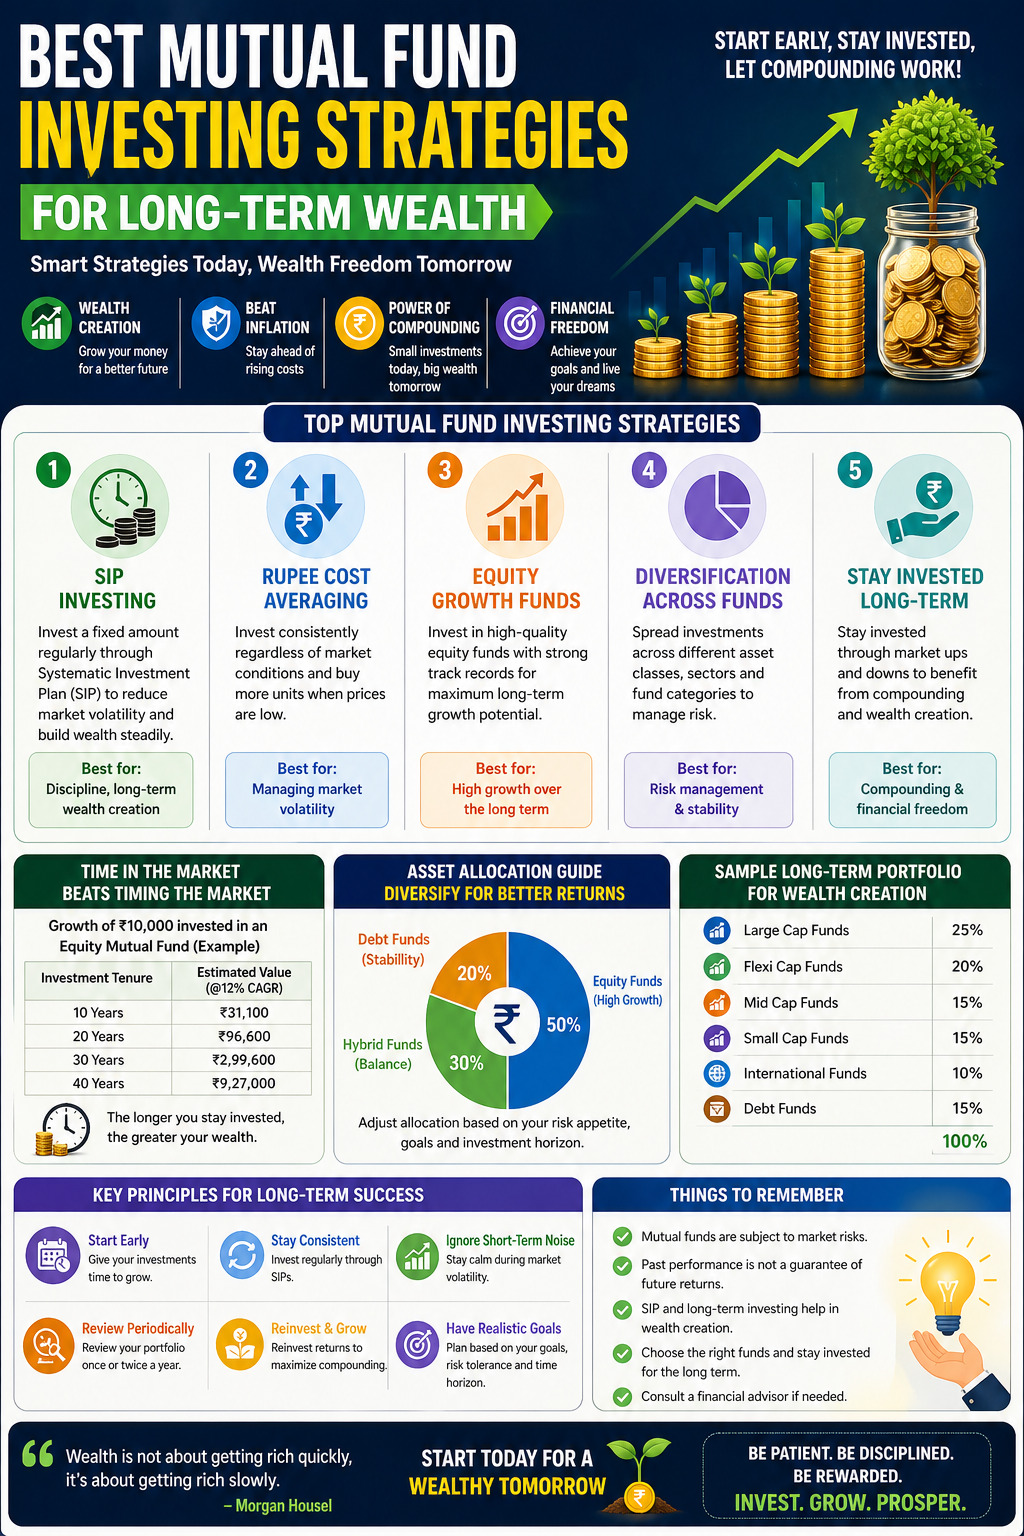
What are mutual fund investing strategies for long-term wealth? Mutual fund investing strategies for long-term wealth are systematic, evidence-based approaches to selecting, allocating, and managing mutual funds over a multi-year horizon, typically 7–20+ years, to achieve financial goals like retirement, children’s education, or generational wealth. They work by combining the power of compounding, rupee-cost averaging, tax efficiency, and diversification across equity, debt, and hybrid instruments. Unlike short-term trading, these strategies prioritise consistency over timing, using frameworks like SIPs, goal-based allocation, and rebalancing to grow capital steadily across market cycles.
Let’s be honest. Inflation is the silent tax most people aren’t accounting for. As of Q1 2025, India’s CPI inflation has hovered around 4.5–5%, according to the Ministry of Statistics and Programme Implementation. That means money sitting in a savings account earning 3.5% is losing real value every single year.
The compounding gap: why timing matters ₹2.12 Cr
What ₹10,000/month SIP in a diversified equity fund could grow to over 25 years at 12% CAGR. The same amount kept in FDs at 6.5% would give you approximately ₹76 lakhs. The gap? Over ₹1.3 crore just from choosing the right instrument.
Three things have made 2025 a particularly critical moment for mutual fund strategy:
First, interest rates are in a transitional phase. The RBI has signalled potential rate cuts in FY25-26, which typically benefits debt funds and makes equity valuations relatively more attractive. Knowing how to position your portfolio ahead of rate cycles is a strategy most retail investors ignore.
Second, the new tax regime is reshaping debt fund attractiveness. After the 2023 amendment removed indexation benefits from debt mutual funds, many investors are confused about where debt fits in their portfolio. (We’ll break this down in the tax section. It’s not as bad as the headlines made it sound.)
Third, passive investing is finally arriving in India. Index funds and ETFs now manage over ₹9 lakh crore, a number that was negligible five years ago. Understanding when to go active vs passive is one of the most important strategic decisions of this decade.
The biggest mistake investors make is treating mutual funds as a product rather than a portfolio. A single SIP into a random fund isn’t a strategy, it’s a lottery ticket with better odds. Dr Priya Srinivasan, CFA, PhD (Finance) – Head of Investment Research, Morningstar India (2025)
These aren’t theories from a textbook. These are frameworks that actually show up in the portfolios of serious long-term investors, the ones who quietly build wealth while others are arguing about which fund to pick.
A Systematic Investment Plan is how most people start with mutual funds, but few understand why it’s so powerful beyond the surface-level explanation. The Securities and Exchange Board of India (SEBI) has consistently highlighted SIPs as the most accessible long-term wealth creation tool for retail investors.
Here’s what the math actually shows. Between 2004 and 2024, a ₹5,000/month SIP in the Nifty 50 TRI index would have grown to approximately ₹1.07 crore from a total investment of ₹12 lakhs. That’s an 8.9x multiplication through two major market crashes (2008, 2020), multiple corrections, and years of sideways movement.
The strategy works because of three compounding forces working simultaneously: price averaging across market cycles, dividend reinvestment, and the mathematical miracle of compounding over long time horizons. The longer you go, the more dramatic the effect.
Strategy Tip
SIP Step-Up: Increase your SIP amount by 10–15% annually as income grows. A ₹10,000 SIP stepped up by 10% yearly gives roughly 2.3x the corpus of a flat ₹10,000 SIP over 20 years using the same total investment period.
Most investors pick funds based on past returns. Smart investors pick funds based on what job those funds need to do. This sounds obvious until you realise almost no one actually does it.
Goal-based allocation works like this: every financial goal gets its own mini-portfolio with an asset mix calibrated to its time horizon and risk tolerance.
| Goal | Time Horizon | Recommended Allocation | Example Fund Types |
|---|---|---|---|
| Retirement corpus | 15–30 years | 80% Equity / 20% Debt | Large-cap index + Flexi-cap + Short-duration debt |
| Child’s education | 8–15 years | 70% Equity / 30% Debt | Multi-cap + Mid-cap + Gilt/Target Maturity |
| Home down payment | 3–7 years | 40% Equity / 60% Debt | Large-cap / Balanced Advantage + Corporate Bond |
| Emergency + liquidity | 0–2 years | 0% Equity / 100% Debt | Liquid funds / Overnight / Ultra-short duration |
The power of goal-based allocation is that it removes emotion from the equation. When markets crash 30%, you don’t panic-sell your retirement corpus because you know you won’t need that money for 20 years. But you also won’t lose sleep if your 2-year home fund is in liquid instruments rather than equity.
This is the strategy used by institutional fund managers and serious HNI investors, and it’s criminally underused by retail investors.
The idea: build a Core (70–75% of portfolio) of low-cost, diversified index funds that will track market performance reliably. Then build a Satellite (25–30%) of higher-conviction, potentially higher-alpha funds: sector plays, mid/small-cap funds, international exposure, or thematic bets.
The core protects you. The satellite gives you upside. And together, they force a level of discipline that pure active investing rarely achieves.
Core-Satellite Example for ₹1 Lakh Monthly Investment
Core (₹72,000): Nifty 50 Index Fund (₹36,000) + Nifty Next 50 Index Fund (₹20,000) + International Index Fund (₹16,000)
Satellite (₹28,000): Mid-Cap Active Fund (₹14,000) + Sectoral/Thematic Fund (₹8,000) + Small-Cap Fund (₹6,000)
Equity-linked savings schemes (ELSS) are the most misunderstood category in Indian mutual funds. People think of them as a tax-saving instrument, which they are, but they miss the bigger picture: ELSS funds are diversified equity funds with a 3-year lock-in, qualifying for ₹1.5 lakh deduction under Section 80C of the Income Tax Act.
Here’s the strategy most people ignore: don’t stop at ₹1.5 lakhs. The tax benefit caps at ₹1.5L, but there’s no rule saying you can’t invest more in the same ELSS fund beyond that cap. You get a good equity fund with professional management, diversification, and forced holding (which prevents panic-selling). That’s valuable regardless of the tax benefit.
According to data from Value Research, the ELSS category has delivered an average 14.2% CAGR over the last 10 years (as of March 2025), outperforming large-cap active funds and comparable to the best flexi-cap funds.
You’ve received a ₹50 lakh bonus. Or inherited money. Or sold property. Now what? Putting it all into equity at once is timing the market. Keeping it in a savings account is wasting it.
The answer is an STP: park the lump sum in a liquid or short-duration debt fund, then systematically transfer ₹2–4 lakhs per month into your target equity funds over 12–18 months. You get market averaging on a large corpus without the psychological agony of watching a lump-sum investment drop 20% in the first month.
Wait, here’s the part nobody tells you. STPs also have tax implications: each transfer counts as a redemption from the debt fund. If you hold the liquid fund for less than 3 years, the gains are taxed as short-term capital gains at your slab rate. Factor this into your calculations, especially for large corpora.
Portfolio rebalancing, bringing your asset allocation back to target by selling winners and buying laggards, is described in almost every investing guide as a risk management tool. And it is. But there’s a hidden wealth effect that most analyses miss.
Rebalancing systematically forces you to buy low and sell high. Not because you’re predicting markets, but because you’re mechanically trimming assets that have outperformed and adding to assets that have underperformed. Academic research from Vanguard’s portfolio research team shows that disciplined annual rebalancing adds roughly 0.35–0.50% in additional returns annually while reducing volatility, a significant long-term difference that compounds quietly over decades.
Rebalance annually or when any asset class drifts more than 5% from its target. Use new contributions to rebalance where possible (avoids tax events). In tax-advantaged instruments, rebalance freely.
This debate has gotten religious in investing circles. The truth, as usual, is more nuanced than the evangelists on either side admit.
The research is actually mixed here, and I mean that literally. S&P SPIVA India Scorecard (2024) shows that over 10 years, approximately 75% of large-cap active funds underperformed the Nifty 50 TRI. That’s a damning statistic. It’s also not the whole picture.
| Falls fully with the market | Active Funds | Passive Funds (Index/ETF) |
|---|---|---|
| Average Expense Ratio | 1.0–1.8% (direct plans) | 0.05–0.20% |
| Large-cap outperformance | ~25% of funds beat index | Tracks index by design |
| Mid/Small-cap | Better alpha potential; ~45% beat benchmark | Fewer good index options |
| Downside protection | Good managers do protect more | Falls fully with market |
| Tax efficiency | More churn = more internal tax drag | Lower portfolio turnover |
| Best use case | Mid/small-cap, international, sectoral | Large-cap, base portfolio core |
The emerging consensus among serious planners: go passive for large-cap exposure (the Indian large-cap market is getting more efficient every year), and consider selective active funds for mid-cap, small-cap, and international allocations where skilled managers can still add meaningful alpha.
Your mileage will vary. A ₹20,000/month SIP investor probably doesn’t need to agonise over this; starting a simple Nifty 50 + Mid-Cap index combo is better than spending 6 months researching and not investing at all. But for portfolios above ₹50 lakhs, this decision can meaningfully affect long-term outcomes.
Each of these links goes into exhaustive detail on a specific strategy covered above with real fund recommendations, historical data, and portfolio templates.
Strategy Guide: The Ultimate SIP Investing Strategy Guide for 2025 → Tax Planning ELSS Funds: How to Save Tax and Build Wealth Simultaneously → Active vs. Passive Index Funds vs Active Funds in India: 2025 Data-Driven Comparison → Portfolio Management How to Rebalance Your Mutual Fund Portfolio Without Losing Money to Tax → Framework Goal-Based Mutual Fund Investing: Build Your Financial Roadmap → Tax Optimization Mutual Fund Taxation in 2025: LTCG, STCG, and Legal Optimization →
I’ve seen every version of this. (Yes, I’ve made a few of these mistakes myself; trust me, I learned this the hard way.) Here’s what actually derails long-term wealth creation:
This section alone could save you lakhs over a lifetime of investing. Indian mutual fund taxation changed significantly in 2023–2024, and most investors haven’t updated their mental models.
Equity and equity-oriented funds held for more than 12 months are subject to Long-Term Capital Gains (LTCG) tax at 12.5% on gains exceeding ₹1.25 lakh per financial year (revised in Budget 2024). Short-term capital gains (held under 12 months) are taxed at 20%.
Strategy: Harvest tax losses in bad years to offset gains in good years. If a fund is down ₹2 lakhs, redeem it, book the loss, and immediately reinvest in a similar (but not identical) fund. This loss can offset future LTCG, and you haven’t actually changed your market exposure meaningfully.
Debt mutual funds no longer benefit from indexation. Gains are taxed at your income slab rate regardless of holding period. This makes debt funds less tax-efficient than they once were, but they’re still useful for liquidity management, capital preservation, and short-term parking. For long-term debt allocation, target maturity funds and dynamic bond funds remain valuable tools despite the tax change.
Tax Optimisation Insight
Spread large redemptions across two financial years to double your ₹1.25 lakh LTCG exemption. If you’re redeeming ₹50 lakhs in equity funds with large gains, redeem half in March and half in April two different FYs, potentially saving ₹15,000+ in tax.
How much should I invest in mutual funds per month for long-term wealth?
Financial planners generally recommend investing 20–30% of monthly take-home income in equity mutual funds for long-term wealth creation. Start with whatever you can sustain, even ₹1,000/month is better than ₹0. Use the 50-30-20 rule: 50% needs, 30% wants, 20% savings/investments. The step-up SIP strategy ensures your investment grows with your income automatically.
Which type of mutual fund is best for long-term wealth creation?
For most investors with 10+ year horizons, diversified equity funds specifically flexi-cap funds, multi-cap funds, or a simple Nifty 50 + Nifty Next 50 index combination, form the best core for long-term wealth. Add a mid-cap fund for higher growth potential if your risk tolerance allows. The specific fund matters less than the category, time horizon, and consistency of investment.
Can mutual funds make you a crore in India?
Absolutely. A ₹10,000/month SIP in a diversified equity fund returning 12% CAGR reaches approximately ₹1 crore in about 20 years. Step up by 10% annually, and that timeline shortens to roughly 16 years, reaching over ₹1.5 crore. The math isn’t magic, it’s compounding. The challenge is starting early and not stopping.
Is it better to invest in SIP or a lump sum in mutual funds?
For salaried investors with a monthly income, SIP wins because it removes timing risk and builds a habit. For windfalls or large lump sums, an STP (Systematic Transfer Plan) strategy is more appropriate: park the money in a liquid fund and transfer to equity monthly over 12–18 months. In a confirmed bull market, lump sum investing can outperform SIPs, but timing markets reliably is nearly impossible for retail investors.
How often should I review my mutual fund portfolio?
Once a year is sufficient for most investors with 10+ year horizons. Review on the same date annually. Check if the allocation has drifted by more than 5–10% from the target. Assess underperforming funds over a 3-year rolling period (not 1-year). Resist the urge to check monthly it leads to emotional decisions that typically hurt returns.
Disclaimer: This article is for educational purposes only and does not constitute personalised financial advice. Mutual fund investments are subject to market risks. Past performance is not indicative of future results. Please consult a SEBI-registered investment advisor before making financial decisions. All statistics cited are based on publicly available data as of April 2025.